Table of Contents Show
Last Updated on – 23-09-2026
The Home Accessibility Tax Credit, usually shortened to HATC, can reduce federal income tax for Canadians who pay for qualifying renovations that make a home safer or more accessible for a senior or a person eligible for the Disability Tax Credit.
The rules have changed considerably since the credit was first introduced. Most importantly, the annual qualifying-expense limit increased from $10,000 to $20,000 from the 2022 tax year onwards.
There has also been another important change. Because the federal rate used for most non-refundable tax credits fell to 14.5% for 2025 and 14% for 2026, the maximum basic HATC tax reduction is now:
| Tax Year | Maximum Eligible Expenses | Credit Rate | Maximum HATC |
| 2024 | $20,000 | 15% | $3,000 |
| 2025 | $20,000 | 14.5% | $2,900 |
| 2026 | $20,000 | 14% | $2,800 |
This means older articles referring to a $10,000 expense limit or $1,500 maximum credit are significantly out of date. Even the commonly quoted $3,000 maximum applies to earlier years rather than the standard 2026 calculation.
The HATC is a non-refundable tax credit. It can reduce federal income tax owed, but it does not by itself create a refund once federal tax payable has been reduced to zero.
Readers unfamiliar with this distinction may find it helpful to understand how non-refundable tax credits work.
What Is the Home Accessibility Tax Credit?
The Home Accessibility Tax Credit provides federal tax relief for qualifying renovations or alterations to an eligible home in Canada.
A renovation generally has to be enduring and integral to the dwelling and must either:
- Allow a qualifying person to gain access to the home.
- Improve their ability to move around or function within it.
- Reduce the risk of injury inside the property.
- Reduce the risk of injury when entering or leaving the property.
The credit is primarily aimed at Canadians who are 65 or older and people who qualify for the Disability Tax Credit, along with certain spouses, relatives and caregivers who pay eligible renovation expenses for them.
A renovation does not automatically qualify merely because it improves a home. Its accessibility or safety purpose matters.
For example, replacing ordinary kitchen cabinets simply because they are old would normally be a general renovation. Lowering cabinets so a wheelchair user can reach them may satisfy the accessibility test.
Who Qualifies for the Home Accessibility Tax Credit?
The rules distinguish between a qualifying individual and an eligible individual.
That distinction is important because the person benefiting from the renovation does not always have to be the person who paid the bill or claims the tax credit.
| Person | Who Can Qualify? |
| Qualifying individual | Someone who is 65 or older at the end of the year |
| Qualifying individual | Someone eligible for the Disability Tax Credit at any point during the year |
| Eligible individual | The qualifying individual’s spouse or common-law partner |
| Eligible individual | Certain relatives who claim, or could qualify to claim, specified dependant or caregiver amounts for the qualifying individual |
| Eligible individual | In certain circumstances, a person entitled to claim the qualifying individual’s transferred disability amount |
Qualifying Individual
A qualifying individual is someone who meets either of these conditions:
- They are 65 years of age or older at the end of the tax year.
- They are eligible for the Disability Tax Credit at any time during the year.
They do not have to meet both conditions.
Eligible Individual
The definition of an eligible individual is more complicated.
A spouse or common-law partner of the qualifying individual can be an eligible individual.
Certain family members may also qualify. These can include a:
- Parent.
- Grandparent.
- Child.
- Child’s spouse or common-law partner.
- Grandchild.
- Brother or sister.
- Aunt or uncle.
- Nephew or niece.
The relationship can be to the qualifying individual or, in relevant circumstances, to their spouse or common-law partner.
However, simply being related is not enough.
The claimant generally needs to have claimed, or have been entitled to claim, a relevant eligible-dependant or caregiver amount for that person.
CRA’s rules also contain situations where the person could have claimed an amount if certain conditions had been different. These include cases where the qualifying individual:
- Had no income.
- Was a child who would have satisfied the relevant rule if aged 18 or older.
- Was not married or living in a common-law relationship for purposes of the eligible-dependant rules.
- Was 65 or older, not entitled to the Disability Tax Credit, and depended on the claimant because of a physical or mental infirmity for purposes of applicable caregiver rules.
Where those rules do not apply, an individual may still qualify if they are entitled to claim the disability amount transferred from the qualifying individual, or would have been entitled if the amount had not been claimed elsewhere.
Because family arrangements can become complicated, particularly where several relatives financially support the same person, claimants should establish eligibility before assuming that paying for a parent’s or relative’s renovation automatically creates an HATC claim.
What Counts as an Eligible Dwelling?
The renovation must be carried out on an eligible dwelling in Canada.
Generally, this is a housing unit owned jointly or otherwise by the qualifying individual and ordinarily inhabited, or expected to be ordinarily inhabited, by them during the year.
A property owned by an eligible individual can also qualify when the relevant conditions are met and both the eligible individual and qualifying individual ordinarily inhabit the home.
A share in a co-operative housing corporation acquired solely to obtain the right to live in the corporation’s housing unit can also satisfy the dwelling rules.
Land forming part of the home can normally be included, generally up to one-half hectare or approximately 1.24 acres.
Can Renters Claim the Federal HATC?
Ordinary tenants generally cannot claim the federal HATC simply because they paid to renovate a rented home. The federal definition of an eligible dwelling is based on qualifying ownership conditions.
Co-operative housing is treated differently because an eligible dwelling can include certain shares in a co-operative housing corporation.
How Much Is the Home Accessibility Tax Credit?
The annual qualifying-expense ceiling remains $20,000.
However, the value of the credit depends on the applicable federal non-refundable tax credit rate for the year.
HATC Examples for the 2025 Tax Year
For 2025, the standard rate is 14.5%.
| Eligible Renovation Cost | Eligible Amount | Approximate 2025 HATC |
| $5,000 | $5,000 | $725 |
| $10,000 | $10,000 | $1,450 |
| $15,000 | $15,000 | $2,175 |
| $20,000 | $20,000 | $2,900 |
| $30,000 | $20,000 maximum | $2,900 |
Spending $30,000 does not create a $4,350 HATC because only the first $20,000 falls within the annual qualifying-expense ceiling.
HATC Examples for the 2026 Tax Year
For 2026, the applicable rate is 14%.
| Eligible Renovation Cost | Eligible Amount | Approximate 2026 HATC |
| $5,000 | $5,000 | $700 |
| $10,000 | $10,000 | $1,400 |
| $15,000 | $15,000 | $2,100 |
| $20,000 | $20,000 | $2,800 |
| $30,000 | $20,000 maximum | $2,800 |
These figures represent the basic federal HATC calculation and assume the claimant has sufficient federal tax payable to use the non-refundable credit.
Home Accessibility Tax Credit Limits by Year
Anyone amending an older return needs to use the rules applying to the year in which the qualifying expenditure was made.
| Tax Year | Maximum Qualifying Expenses | Standard Credit Rate | Maximum Basic Credit |
| 2015 | $10,000 | 15% | $1,500 |
| 2016 | $10,000 | 15% | $1,500 |
| 2017 | $10,000 | 15% | $1,500 |
| 2018 | $10,000 | 15% | $1,500 |
| 2019 | $10,000 | 15% | $1,500 |
| 2020 | $10,000 | 15% | $1,500 |
| 2021 | $10,000 | 15% | $1,500 |
| 2022 | $20,000 | 15% | $3,000 |
| 2023 | $20,000 | 15% | $3,000 |
| 2024 | $20,000 | 15% | $3,000 |
| 2025 | $20,000 | 14.5% | $2,900 |
| 2026 | $20,000 | 14% | $2,800 |
The $20,000 annual expense limit itself has not been cut for 2026. The lower maximum credit results from the reduction in the federal rate applied to most non-refundable tax credits.
What Home Accessibility Expenses Can Be Claimed?
Eligible expenditure can include the reasonable cost of goods and services directly attributable to the qualifying renovation.
Examples may include:
- Building materials.
- Permanent fixtures.
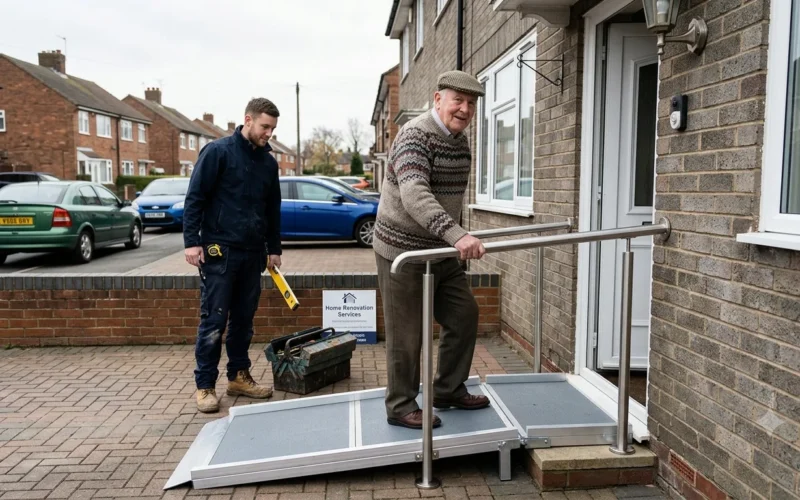
- Wheelchair ramps.
- Accessibility-related handrails.
- Grab bars and their necessary structural reinforcement.
- Accessible showers.
- Wider doorways.
- Appropriate non-slip flooring.
- Accessible counters and cupboards.
- Stair or wheelchair lifts that form part of the home.
- Building plans.
- Necessary permits.
- Equipment rental used for the renovation.
- Labour supplied by qualifying professional contractors.
The key issue is not the name of the product but why it was installed and whether the work forms an enduring part of the eligible dwelling.
What Expenses Cannot Be Claimed?
HATC does not cover every cost connected with accessibility or home ownership.
Generally ineligible expenses include:
- Purchasing a property.
- Annual or recurring maintenance.
- Ordinary home repairs.
- Household appliances.
- Electronic home-entertainment equipment.
- Housekeeping.
- Gardening.
- Outdoor maintenance services.
- Security-monitoring services.
- Financing charges or loan interest.
- Renovations undertaken mainly to increase or preserve the property’s market value.
- Your own labour.
- The value of tools you already own.
A portable item that does not become an enduring part of the dwelling will also generally fall outside the federal HATC rules.
For that reason, the FAQ in the previous version of this article suggesting that ordinary wheelchairs and walkers were examples of HATC expenses was misleading. Those are not home renovations merely because they assist mobility.
What Happens If You Do the Work Yourself?
DIY renovations can qualify, but only certain costs can be included.
A homeowner doing the work personally may generally claim qualifying:
- Materials.
- Fixtures.
- Building plans.
- Permits.
- Equipment rentals.
They cannot assign a dollar value to their own time and claim it as labour.
The value or purchase cost of their own tools is also not treated as a qualifying HATC labour expense.
Can You Pay a Family Member to Do the Renovation?
Special rules apply when goods or services are supplied by someone related to the qualifying individual or eligible individual.
The expense will generally not qualify unless that related person is registered for GST/HST under the relevant tax rules.
Before paying a related contractor, verify their registration through the CRA’s GST/HST Registry and keep their registration number with the invoice.
Business owners who need more background on registration numbers can read about the GST registration process in Canada.
This is particularly important because simply putting a GST/HST number on an invoice does not establish that the registration is valid.
What If the Person Has More Than One Home During the Year?
A qualifying person can have only one eligible dwelling at any particular time but can have more than one eligible dwelling during the same tax year.
The most obvious example is someone who sells one home and moves into another during the year.
This does not provide a separate $20,000 HATC ceiling for each property.
Example
Suppose an eligible senior spends:
- $8,000 adapting their original home before moving.
- $17,000 adapting their new home later in the same year.
Total accessibility expenses are $25,000.
The maximum qualifying expenditure for that individual remains $20,000 across the eligible dwellings combined.
The remaining $5,000 does not create an additional HATC simply because it relates to a second home.
What If More Than One Qualifying Person Lives in the Home?
Where more than one qualifying individual uses the same eligible dwelling, the annual qualifying expenditure limit for that dwelling does not multiply automatically.
The total eligible expenses are generally capped at $20,000 for the dwelling.
The qualifying individual and eligible family members can split the claim between themselves, but they cannot collectively claim the same expenditure more than permitted.
If the claimants cannot agree on the allocation, CRA can determine the amounts.
Can Condo and Co-op Owners Claim Common-Area Renovations?
Yes, in qualifying circumstances.
This is one of the more easily overlooked HATC rules.
An eligible condominium or co-operative resident may be able to claim their share of qualifying accessibility renovation expenses relating to common areas.
For example, a condominium corporation might install an accessibility modification in a shared entrance.
The claimant does not simply claim the corporation’s entire project cost. They need documentation showing their allocated share.
The condominium, co-operative or syndicate should provide a statement identifying matters such as:
- The renovation cost.
- The claimant’s share.
- The contractor.
- The contractor’s business address.
- GST/HST registration details where applicable.
- The work performed.
- The dates on which it was completed.
That statement should be kept with the taxpayer’s supporting records.
What If Part of the Home Is Used for Business or Rental Income?
A home does not automatically become ineligible just because part of it generates business or rental income.
However, the claimant generally cannot use HATC for the income-producing share of the expenditure.
If an accessibility renovation applies exclusively to the personal-use portion of the dwelling, the eligible personal amount may qualify.
Where an improvement benefits the entire property or a shared area, the cost needs to be reasonably apportioned between personal use and income-producing use.
Example
Suppose a homeowner spends $12,000 installing an accessibility ramp that benefits a property used:
- 75% personally.
- 25% for an income-producing activity.
If the circumstances support that allocation, only the personal-use portion would normally be considered for HATC purposes.
That would be:
$12,000 × 75% = $9,000
The claimant should retain evidence supporting the chosen allocation rather than selecting an arbitrary percentage.
Do Government Grants Reduce the HATC Claim?
Generally, no.
Federal HATC eligible expenses are not reduced merely because the claimant also receives qualifying assistance from a federal, provincial or territorial government.
That can include:
- Grants.
- Forgivable loans.
- Tax credits.
Reasonable vendor or manufacturer rebates and incentives also generally do not reduce the amount of an otherwise eligible HATC expense.
However, a separate grant or provincial program can have its own eligibility and reporting rules, so receiving federal HATC relief should not be treated as proof that another program permits the same treatment.
Can HATC and Medical Expenses Be Claimed Together?
This rule changed from January 1, 2026.
Readers need to distinguish between the 2025 tax year and expenses incurred in 2026 or later.
For information about qualifying healthcare costs generally, see how medical expenses can be claimed on Canadian taxes.
Expenses Incurred in 2025
For qualifying expenses incurred under the rules applying to the 2025 tax year, an expense that satisfied both sets of conditions could generally be claimed for both:
- Home Accessibility Tax Credit.
- Medical Expense Tax Credit.
Simplified 2025 Example
Assume a taxpayer:
- Has net income of $50,000.
- Incurs $20,000 of renovation costs.
- The entire $20,000 independently satisfies both HATC and METC requirements.
- Has sufficient tax payable to use the credits.
- Has no other relevant medical expenses for this simplified illustration.
For 2025:
HATC
$20,000 × 14.5% = $2,900
For the medical expense calculation, 3% of $50,000 is:
$1,500
If that is the applicable medical-expense threshold:
$20,000 − $1,500 = $18,500
A simplified federal METC calculation at 14.5% would therefore be:
$18,500 × 14.5% = $2,682.50
The example illustrates why qualifying the same expense under both programs could have been valuable in 2025.
Actual METC calculations can differ because of other medical expenses, the selected 12-month period, income, dependants, provincial credits and other tax-return factors.
Expenses Incurred From January 1, 2026
The federal rules changed for the 2026 and subsequent tax years.
An expense included in a Medical Expense Tax Credit claim cannot also be treated as a qualifying HATC expenditure.
Therefore, taxpayers with an expense that appears to meet both sets of rules may need to determine which treatment is more beneficial rather than automatically claiming both.
This replaces the previous article’s “double credit” or “triple credit” approach, which would be misleading for current 2026 expenses.
Are There Provincial Home Accessibility Credits?
The federal HATC applies across Canada, but some provinces operate separate programs with their own rules.
For example, British Columbia has a Home Renovation Tax Credit for Seniors and Persons with Disabilities. It is refundable and can provide up to $1,000, calculated as 10% of up to $10,000 in qualifying renovation expenses.
New Brunswick also maintains a Seniors’ Home Renovation Tax Credit. Eligible residents can claim 10% of up to $10,000 of qualifying expenditure, for a maximum refundable credit of $1,000.
These provincial programs should not be described simply as a universal “second” or “third” HATC. Eligibility, age, disability, residence, renovation and claiming rules differ by province.
Taxpayers should therefore examine their province’s current rules separately when preparing the return.
How to Claim the Home Accessibility Tax Credit?
The current federal claiming process is simpler than the old article suggested.
Step 1: Confirm the Person Qualifies
Establish that there is a qualifying individual who is:
- At least 65 at the end of the year, or
- Eligible for the Disability Tax Credit.
If another family member is making the claim, make sure that person satisfies the eligible-individual rules.
Step 2: Confirm the Home Qualifies
Check that the property satisfies the ownership and ordinary-residence requirements for an eligible dwelling.
Step 3: Review Each Renovation
Confirm that each expense is directly connected to an enduring renovation intended to:
- Improve access.
- Improve mobility or functionality.
- Reduce the risk of harm.
Step 4: Total the Eligible Expenses
Apply the applicable $20,000 annual ceiling and the rules for multiple claimants or multiple dwellings.
Step 5: Complete the Federal Worksheet
For the 2025 tax return, use the relevant Federal Worksheet calculation for line 31285.
The old instruction telling taxpayers to complete a federal “Schedule 12” for HATC should not be retained in the article.
Step 6: Enter the Amount on Line 31285
Transfer the calculated home accessibility expense amount to line 31285 of the federal income tax return.
Tax software will normally guide eligible filers through the corresponding calculation.
Step 7: Keep the Evidence
Supporting paperwork is generally kept rather than submitted with the original tax return.
CRA can request it later.
Documents to Keep for a HATC Claim
Documentation is especially important for an accessibility renovation because CRA may need to establish both what was purchased and why the work qualifies.
Keep invoices, receipts, contracts and other records showing, where applicable:
- Vendor name: The person or business that supplied the work or materials.
- Business address: The contractor or supplier’s address.
- GST/HST number: Where applicable.
- Goods purchased: A clear description and quantity.
- Purchase date: When the goods were bought.
- Delivery date: Including delivery slips where available.
- Work performed: A sufficiently detailed description of the renovation.
- Property address: Where the work was completed.
- Completion date: When services were performed.
- Invoice total: The amount charged.
- Proof of payment: Such as a paid invoice, bank record, credit-card record or cancelled cheque.
- Condo/co-op allocation: A signed statement showing the claimant’s share of common-area costs where relevant.
- Plans and permits: Where they form part of the qualifying expense.
A vague invoice stating only “home renovation – $12,000” provides much less evidence than an invoice explaining that the contractor widened specified doorways, installed an accessibility ramp and fitted bathroom grab-bar reinforcement.
How to Verify a Contractor’s GST/HST Registration?
This is particularly important when a relative performs paid work.
The invoice should contain the contractor’s identifying information and GST/HST registration number where required.
Claimants can use CRA’s GST/HST Registry to confirm whether the number and business details are valid for the relevant transaction date.
Keep evidence of the verification with the renovation paperwork where practical.
How to Choose a Qualified Accessibility Renovator?
Tax eligibility is only one part of an accessibility project. The renovation also needs to be safe and appropriate for the person who will use it.
Before hiring someone, consider:
- Experience with accessibility or aging-in-place renovations.
- Knowledge of ramps, slopes, zero-step entrances and accessible bathrooms.
- Appropriate licensing and insurance where required.
- GST/HST registration.
- Written quotations.
- Detailed contracts.
- Clear invoices.
- References from comparable projects.
- Knowledge of applicable permits and building requirements.
- Willingness to work with occupational therapists or other specialists where necessary.
The Canadian Home Builders’ Association also recognises Qualified Adaptiv Home Specialists, including renovators, designers and other professionals who have completed specialised training relating to accessible and aging-in-place renovations.
The designation is not a condition for receiving HATC, but it can be one useful credential to consider when selecting someone for specialised accessibility work.
Frequently Asked Questions
What is the Home Accessibility Tax Credit?
The HATC is a federal non-refundable tax credit for eligible expenses incurred on qualifying renovations that improve accessibility, mobility, functionality or safety for a qualifying senior or person eligible for the Disability Tax Credit.
What is the HATC limit in 2026?
Up to $20,000 of qualifying expenses can generally be claimed. At the 2026 14% federal credit rate, that represents a maximum basic HATC value of $2,800, subject to the claimant’s tax position.
Was the HATC maximum ever $3,000?
Yes. The qualifying-expense limit increased to $20,000 from 2022. At the former 15% credit rate, that produced a maximum credit of $3,000. The rate fell to 14.5% for 2025 and 14% for 2026.
Can a senior claim HATC without having a disability?
Yes. Someone who is at least 65 years old at the end of the tax year can be a qualifying individual without also qualifying for the Disability Tax Credit.
Can someone under 65 qualify?
Yes, if the individual is eligible for the Disability Tax Credit during the year.
Can a family member claim for a senior?
Potentially. A spouse, common-law partner or certain other relatives may qualify as an eligible individual, but detailed dependant, caregiver or disability-transfer rules can apply.
Can renters claim HATC?
The federal credit generally requires an eligible dwelling meeting specified ownership requirements. An ordinary tenant does not qualify merely because they paid for renovations. Special rules apply to certain co-operative housing interests.
Can condo owners claim accessibility work in common areas?
Potentially, yes. A qualifying condo owner’s allocated share of eligible common-area renovation costs can count, provided appropriate documentation from the condominium corporation or equivalent body is retained.