Table of Contents Show
Last Updated – 07-10-2026
The Disability Tax Credit (DTC) is a federal non-refundable tax credit for people with severe and prolonged impairments in physical or mental functions, or for supporting family members who can claim an unused amount.
For the 2026 tax year, the federal disability amount is $10,341. At the 2026 lowest federal tax rate of 14%, that can reduce federal income tax by up to approximately $1,448.
A person under 18 may also qualify for a federal disability supplement of up to $6,032.
The most important point is that the DTC is not a cash benefit by itself. It is one of Canada’s non-refundable tax credits, meaning it can reduce income tax payable to zero but does not normally generate a payment for unused credit.
However, DTC approval can be financially important even for someone who pays little or no income tax because it may open access to the Canada Disability Benefit, Registered Disability Savings Plan, Child Disability Benefit and Canada Workers Benefit disability supplement.
How Much Is the Disability Tax Credit Worth in 2026?
There are two figures readers should not confuse: the disability amount and the tax reduction.
The $10,341 federal amount is not a $10,341 refund. It is multiplied by the lowest federal income-tax rate.
$10,341 × 14% = $1,447.74
That gives a maximum federal reduction of approximately $1,448, assuming the person claiming the credit has enough federal income tax payable to use it.
This is also why some older online DTC figures are misleading. The federal DTC amount for 2025 was $10,138, not $10,341. The $10,341 figure applies to 2026.
DTC Amount for a Child Under 18
A person who is under 18 at the end of the tax year may qualify for the basic disability amount plus the child supplement.
For 2026:
$10,341 basic amount + up to $6,032 supplement = up to $16,373 of federal disability amounts.
At a 14% federal rate, that represents a theoretical maximum federal tax reduction of approximately $2,292.
The child supplement can be reduced where certain child-care or attendant-care expenses are claimed, so $2,292 should not be treated as a guaranteed saving.
How Much Could the DTC Be Worth by Province?
The federal DTC is supplemented by provincial or territorial disability tax credits. Consequently, two Canadians with otherwise identical circumstances can receive different combined tax reductions depending on where they live.
The following figures are planning estimates for an adult in 2026, calculated using the 2026 provincial or territorial disability amount and the applicable lowest tax rate.
They assume enough income tax is payable to use the full credit. Québec is shown separately because it operates its own provincial tax system.
| Province or Territory | 2026 Disability Amount | Approx. Provincial Reduction | Approx. Federal + Provincial Reduction |
| Alberta | $17,563 | $1,405 | $2,853 |
| British Columbia | $9,913 | $555 | $2,003 |
| Manitoba | $6,180 | $667 | $2,115 |
| New Brunswick | $10,210 | $960 | $2,407 |
| Newfoundland and Labrador | $7,549 | $657 | $2,105 |
| Nova Scotia | $7,341 | $645 | $2,093 |
| Northwest Territories | $14,758 | $871 | $2,318 |
| Nunavut | $16,733 | $669 | $2,117 |
| Ontario | $10,494 | $530 | $1,978 |
| Prince Edward Island | $6,890 | $665 | $2,113 |
| Saskatchewan | $14,266 | $1,498 | $2,946 |
| Yukon | $10,341 | $662 | $2,110 |
| Québec | Separate provincial system | Separate calculation | Separate calculation |
B.C., for example, officially lists a $9,913 disability amount for 2026, confirming the provincial amount used above.
Québec instead provides its own Amount for a Severe and Prolonged Impairment in Mental or Physical Functions.
Revenu Québec lists the 2026 amount at $4,208, so readers in Québec should not simply apply the federal/provincial calculation used for the other provinces.
Worked Example: Ontario Adult
An Ontario adult approved for the full 2026 amount could have:
Federal reduction: $10,341 × 14% = $1,447.74
Ontario reduction: $10,494 × 5.05% = approximately $529.95
Combined potential reduction: approximately $1,977.69
This is a reduction of tax payable, not an automatic $1,978 cheque.
Worked Example: British Columbia Adult
Federal reduction: approximately $1,447.74
B.C. reduction: $9,913 × 5.6% = approximately $555.13
Combined potential reduction: approximately $2,002.87
Worked Example: Alberta Adult
Federal reduction: approximately $1,447.74
Alberta reduction: $17,563 × 8% = approximately $1,405.04
Combined potential reduction: approximately $2,852.78
The Alberta figure is worth noting because calculations using an older 10% provincial lowest rate can materially overstate the 2026 benefit.
Worked Example for a Child
For an eligible Ontario child, the federal and provincial supplements could increase the theoretical combined tax reduction to approximately $3,131, before considering the rules that reduce the child supplement for certain attendant-care and child-care expenses.
Comparable theoretical totals are around $3,171 in British Columbia and $4,752 in Alberta.
These figures illustrate the calculation rather than guaranteeing a refund. The family’s actual result depends on tax payable, who claims or receives a transfer of the credit, other tax credits and applicable child-supplement reductions.
Who Qualifies for the Disability Tax Credit?
The DTC does not operate from a simple list of diagnoses. Except where special rules apply, CRA focuses on the functional effects of an impairment.
A medical practitioner generally needs to certify that the person meets one of three pathways:
- Marked restriction in one basic activity of daily living
- Cumulative effect of significant limitations in two or more categories
- Qualifying life-sustaining therapy
CRA’s current Disability Tax Credit eligibility criteria set out the detailed tests.
The 3-Times-Longer Test
A marked restriction generally exists where the person is either unable to perform the relevant activity or takes three times as long as a person of a similar age without the impairment, even when appropriate therapy, medication and devices are used.
The 90% Test
The restriction must be present all or almost all of the time, which CRA generally interprets as at least 90% of the time.
The 12-Month Test
The impairment must have lasted, or be expected to last, for a continuous period of at least 12 months.
These thresholds are critical. A serious diagnosis on its own does not necessarily satisfy the DTC rules.
What Activities Does CRA Consider?
CRA considers restrictions involving:
| Category | Examples of What CRA Assesses | Current Professionals Who Can Certify |
| Vision | Severe loss of visual acuity or field of vision | Doctor, nurse practitioner, optometrist |
| Walking | Ability and time required to walk | Doctor, nurse practitioner, occupational therapist, physiotherapist |
| Mental functions | Adaptive functioning, attention, concentration, judgement, memory and other everyday mental functions | Doctor, nurse practitioner, psychologist |
| Dressing | Ability to put on and remove clothing | Doctor, nurse practitioner, occupational therapist |
| Feeding | Ability to prepare food for oneself and feed oneself | Doctor, nurse practitioner, occupational therapist |
| Eliminating | Managing bowel or bladder functions | Doctor, nurse practitioner |
| Hearing | Ability to hear sufficiently for everyday communication | Doctor, nurse practitioner, audiologist |
| Speaking | Ability to speak so as to be understood | Doctor, nurse practitioner, speech-language pathologist |
| Life-sustaining therapy | Qualifying therapy required to sustain a vital function | Doctor, nurse practitioner |
A medical doctor or nurse practitioner can currently certify all impairment categories. Other practitioners are restricted to particular areas.
This is important because the expanded practitioner rules announced in Spring Economic Update 2026 are proposed changes for certificates issued after 2026, rather than rules applicants should automatically assume are already available in 2026.
How Does the Cumulative Effect Rule Work?
Someone does not necessarily need a marked restriction in one category.
The cumulative-effect provision can apply where a person has significant limitations in two or more eligible categories and the limitations:
- Occur together at least 90% of the time;
- Have lasted or are expected to last at least 12 continuous months; and
- Together produce an effect equivalent to being unable, or taking three times longer, to carry out one basic activity of daily living.
Life-sustaining therapy is not one of the categories combined under this test.
This rule can be particularly important for people whose impairments affect several daily functions without one individual limitation being severe enough to pass the marked-restriction test by itself.
What Counts as Life-Sustaining Therapy?
For 2021 and later years under the current rules, qualifying therapy generally must:
- Be required to support a vital function;
- Be required at least twice per week;
- Take an average of at least 14 hours per week of qualifying therapy-related time; and
- Relate to an impairment lasting or expected to last at least 12 months.
The twice-per-week rule matters because some older DTC material still refers to three times per week. That was part of the previous test.
Time directly associated with administering therapy, determining certain dosages, maintaining required therapy records and maintaining equipment can count.
Travel, ordinary exercise, obtaining medication and many routine medical appointments generally do not.
Type 1 Diabetes
People diagnosed with Type 1 diabetes are deemed to meet the frequency and 14-hour requirements for life-sustaining therapy for 2021 and subsequent years under the applicable rules.
A practitioner therefore does not have to establish those two elements in the same way as for most other therapies.
Can ADHD Qualify for the Disability Tax Credit?
Yes, potentially, but ADHD diagnosis by itself does not automatically qualify someone for the DTC.
The relevant question is usually how ADHD affects mental functions necessary for everyday life. The impairment must satisfy the marked-restriction test or, where applicable, contribute to qualifying cumulative effects.
A practitioner should therefore describe actual functional limitations rather than simply write “ADHD”.
For example, evidence may address substantial and persistent limitations involving attention, concentration, goal-setting, judgement, memory, adaptive functioning or completing essential everyday tasks.
Can Anxiety Qualify for the Disability Tax Credit?
Severe anxiety can qualify, but diagnosis alone is not sufficient.
An anxiety disorder may satisfy the mental-functions category where its effects are severe and prolonged enough to cause a marked restriction in everyday mental functions.
That means the evidence needs to establish the functional impact and the CRA thresholds: typically the three-times-longer, 90% and 12-month tests, or the cumulative-effect rules where appropriate.
A statement that someone “has anxiety” without explaining how the condition restricts essential everyday functioning is much less informative for a DTC determination.
Can Arthritis Qualify for the DTC?
Yes, severe arthritis can potentially qualify, but again, the diagnosis is not the test.
Depending on the person, arthritis could affect walking, dressing or feeding. Someone who experiences limitations across multiple categories may also need to consider the cumulative-effect rules.
The application should explain what the person is unable to do, how long activities take, how often the limitations occur, what treatment or devices are used and how long the impairment has lasted.
How to Apply for the Disability Tax Credit in 2026?
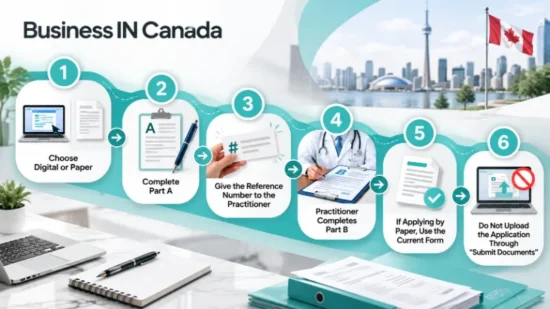
The old advice to simply download Form T2201, have Part B completed and mail it is no longer the best description of the process.
CRA now provides digital and paper routes, and applicants should use one route consistently.
Step 1: Choose Digital or Paper
CRA says Part A and Part B must use the same application method. A mixed-format application cannot be processed as a normal complete application.
Step 2: Complete Part A
For the digital application, the person with the impairment or their legal representative can complete Part A through their CRA account.
Part A can also be completed by phone with CRA, including through an agent or automated service.
The applicant provides personal information, information about a supporting family member where relevant and consent regarding CRA contact and possible prior-year adjustments.
Step 3: Give the Reference Number to the Practitioner
After digital Part A is submitted, CRA provides a reference number.
The applicant gives this number to the appropriate medical practitioner, who uses it to complete Part B digitally.
The reference number is valid for up to 12 months and can be used once for the practitioner’s digital Part B submission.
Step 4: Practitioner Completes Part B
The practitioner explains the effects of the impairment and certifies the applicable category.
CRA says practitioners may base their assessment on symptoms reported by the patient, medical history, direct observations and their knowledge of how the impairment affects the patient.
This is why functional evidence is so important.
Step 5: If Applying by Paper, Use the Current Form
CRA currently directs applicants to use the recent Form T2201 version, identified as 23e or 23f on its application page.
As of September 8, 2026, Form T2201 versions from before 2023 are no longer accepted.
Step 6: Do Not Upload the Application Through “Submit Documents”
This is an important 2026 change.
Since July 14, 2026, a DTC application cannot ordinarily be submitted through the “Submit documents” function in a CRA account. Applicants should use the digital DTC process or mail the paper application.
The Submit Documents service can still be used where CRA specifically asks for further information and provides instructions for doing so.
Is There a Fixed Ontario Fee for Completing the DTC Form?
There is no CRA-set $44.95 Ontario DTC application fee that should be presented as a standard charge.
CRA states that a medical practitioner may charge a fee, and the applicant is responsible for it. The amount depends on the practitioner or clinic.
The fee may in some circumstances be claimable as a medical expense on the tax return. CRA identifies the relevant medical-expense lines as 33099 or 33199.
Readers considering that deduction may also want to understand medical expenses on a Canadian tax return.
How Long Does CRA Take to Process a DTC Application?
For 2026–27, CRA’s service standard is to issue a Notice of Determination within eight weeks of receiving a complete DTC certificate, with a target of meeting that standard 95% of the time.
The eight-week standard does not apply where CRA needs to contact the applicant or practitioner for additional information.
This is more reliable than quoting broad estimates such as “three to six months” as though they were CRA’s normal target.
What Happens After CRA Reviews the Application?
CRA compares the medical information in the application with the statutory DTC eligibility requirements.
There are three broad outcomes:
Approved: CRA issues a Notice of Determination confirming the years for which the person is eligible.
More information needed: CRA may contact the practitioner and request additional documentation or clarification.
Disallowed: CRA explains that the information provided did not establish eligibility.
A returned incomplete form should not automatically be described as a denial.
CRA may return paper applications because of missing signatures, missing mandatory information, separate Part A and Part B submissions, illegible information or other completion problems.
Common DTC Application Mistakes
One of the biggest mistakes is concentrating on the name of the condition instead of its functional effects.
A stronger application gives the practitioner enough accurate information to explain how the impairment affects activities covered by the DTC rules.
Common problems include:
- Describing a diagnosis but not its day-to-day functional impact;
- Failing to address the three-times-longer threshold where relevant;
- Failing to explain that restrictions occur at least 90% of the time;
- Not establishing the continuous 12-month period;
- Overlooking cumulative effects across two or more categories;
- Using an outdated T2201;
- Mixing digital and paper methods;
- Missing applicant or practitioner signatures on a paper form;
- Leaving required personal details incomplete; and
- Assuming eligibility for another disability program automatically proves DTC eligibility.
The application should be accurate rather than exaggerated. The practitioner’s role is to give their professional assessment of the actual impairment and its effects.
What If Your Doctor Will Not Complete the DTC Form?
First, ask why.
The practitioner may believe the DTC criteria are not met, may lack enough information about the functional limitations, or may believe another professional is better positioned to assess the relevant impairment.
Applicants can bring concrete information such as treatment history, medical reports and examples showing how long essential activities take, how often the limitation occurs and what assistance, therapy or devices are required.
Depending on the category, another qualified professional may be able to certify Part B. For example, a psychologist can certify mental functions, an optometrist vision, an audiologist hearing and an occupational therapist walking, feeding or dressing.
The professional still has to reach their own clinical judgement; changing practitioners does not change the legal DTC eligibility threshold.
What Can You Do If the DTC Is Denied?
A denial is not necessarily the end of the process.
CRA says a person who disagrees with the decision may:
- Contact CRA to discuss the determination;
- Request a review and provide new or updated medical evidence; or
- File a formal income-tax objection.
A formal objection must generally be filed within 90 days of the date on the Notice of Determination.
New evidence should address the reason for the original disallowance rather than merely repeating the diagnosis.
How Do You Claim the Disability Tax Credit?
Once CRA approves the DTC, the amount can be claimed on the income-tax return.
The main federal lines are:
| Situation | Tax Return Line |
| Claiming your own disability amount | Line 31600 |
| Amount transferred from a dependant | Line 31800 |
| Transfer from spouse or common-law partner | Line 32600 |
If the person with the impairment cannot use all of the credit to reduce their own tax, some or all of the unused disability amount may be transferred to a qualifying supporting family member, subject to CRA’s support and relationship rules.
More than one eligible supporter can sometimes share a transferred amount, but the combined claims cannot exceed the amount CRA allows for that dependant.
Can the DTC Be Claimed Retroactively?
Yes.
If CRA approves eligibility for previous years and the DTC was not previously claimed, tax returns can generally be adjusted for up to 10 previous years.
An applicant can authorize CRA to make previous-year adjustments through the DTC application, or request adjustments separately after approval.
Retroactive approval can therefore produce a substantial refund in some cases, but 10 years of eligibility does not guarantee a large cheque.
The result depends on factors such as:
- How much tax was actually payable in each eligible year;
- Whether someone else can claim an unused transferred amount;
- Which years CRA approves; and
- The federal and provincial DTC amounts applicable in each year.
The Non-Refundable DTC Trap: Approval Does Not Always Mean a Cheque
This is one of the most misunderstood parts of the DTC.
Suppose an approved adult has a theoretical $1,448 federal DTC reduction but already owes $0 federal income tax after their other credits.
The DTC cannot reduce their federal tax below zero, so the unused amount does not become a $1,448 cash payment to them.
However, there may still be value through a permitted transfer to a supporting relative or through DTC-linked programs such as the Canada Disability Benefit or RDSP.
This is also why a person can be approved retroactively for several years yet receive a much smaller refund than expected—or no DTC tax refund personally.
What Benefits Can DTC Approval Unlock?
DTC approval is important because it acts as a gateway to several other programs.
Canada Disability Benefit
For the payment period from July 2026 to June 2027, the maximum Canada Disability Benefit is $204.20 per month, or $2,450.40 over 12 months.
The amount is income-tested. DTC approval is required, but it is not the only eligibility requirement.
A further $150 lump-sum supplemental payment was introduced to help offset the cost of obtaining DTC certification.
The regulatory change took legal effect on September 1, 2026, and the first eligible payments began on September 17, 2026. No separate application is required for people who qualify for the supplemental payment.
Child Disability Benefit
For July 2026 to June 2027, the Child Disability Benefit can provide up to $290 per month, or $3,480 per year for each eligible child, depending on adjusted family net income.
Registered Disability Savings Plan
DTC eligibility can allow a person to become an RDSP beneficiary.
Depending on income, contributions and other rules, the federal government can provide up to:
- $3,500 per year through the Canada Disability Savings Grant, with a $70,000 lifetime grant limit; and
- $1,000 per year through the Canada Disability Savings Bond, with a $20,000 lifetime bond limit.
The bond does not require the beneficiary to make a personal contribution. Carry-forward rules can also result in larger amounts in some years.
Canada Workers Benefit Disability Supplement
Workers with lower incomes who qualify for the DTC may also qualify for the disability supplement to the Canada Workers Benefit.
CRA’s current outreach material lists a disability supplement of up to $860, although actual entitlement depends on income and province or territory.
More detail on the underlying benefit is available in the Canada Workers Benefit 2026 increase.
Home Accessibility Tax Credit
A person eligible for the DTC can potentially qualify for the Home Accessibility Tax Credit where eligible renovations improve access, mobility, functionality or safety in a qualifying home.
The HATC applies to up to $20,000 of eligible expenditure per year per eligible dwelling.
Canada Caregiver Amount
Supporting relatives may also qualify for a Canada caregiver amount in appropriate circumstances.
However, this is a separate tax measure with its own requirements. A DTC approval should not be presented as automatically creating caregiver-credit entitlement.
Can Newcomers and Temporary Residents Apply for the DTC?
DTC medical eligibility is centred on the person’s impairment and the required practitioner certification. CRA’s DTC eligibility page does not impose a rule that the applicant must specifically be a Canadian citizen or permanent resident before their impairment can meet the DTC medical test.
That does not mean every DTC-linked program has the same rules.
For example, the Canada Disability Benefit separately requires the applicant to be a Canadian resident for income-tax purposes and fall into an eligible status category.
A temporary resident generally must have lived in Canada throughout the previous 18 months, among the other CDB conditions.
Newcomers should therefore distinguish between DTC eligibility and the separate residence, immigration-status, age, income and tax-filing requirements of each benefit the DTC may unlock.
Where Can You Get Help With a DTC Application?
The first place to check should generally be CRA’s own DTC information and application service.
Community disability organizations and appropriate tax-help services may also be useful, particularly where someone needs assistance understanding forms or tax adjustments.
Paid DTC application firms are optional. Applicants should understand exactly what the firm charges, whether the fee is fixed or percentage-based, and whether additional charges apply to retroactive tax refunds or benefit claims before signing an agreement.
A medical professional can also charge for completing the medical portion. There is no reason to present a single unverified Ontario figure such as $44.95 as the standard DTC fee.
Where a medical-practitioner fee qualifies under CRA’s rules, it may potentially be included as a medical expense.
What Changed for the Disability Tax Credit in 2026?
Several distinct changes need to be separated because some are already in force and others remain proposed.
Federal DTC Amount Increased to $10,341
For 2026, the federal disability amount is $10,341, compared with $10,138 for 2025.
Despite the larger base amount, the maximum 2026 federal tax reduction is about $1,448 because the applicable lowest federal rate is 14%.
Older T2201 Forms Stopped Being Accepted
From September 8, 2026, CRA stopped accepting T2201 versions dating from before 2023.
CRA Account “Submit Documents” Route Changed
From July 14, 2026, DTC applications can no longer normally be uploaded through the general Submit Documents section of CRA accounts. Applicants use the digital DTC form or mail the paper application instead.
Streamlined Certification for Certain Conditions Is Proposed
The federal government’s Spring Economic Update 2026 proposed a streamlined certification process for more than 40 specified long-lasting medical conditions.
The official proposed list includes conditions such as Alzheimer’s disease, ALS, severe cerebral palsy, Down syndrome, advanced or severe Parkinson’s disease, schizophrenia, severe stroke and severe traumatic brain injury.
Under the proposal, a qualified practitioner would certify the listed diagnosis without completing the same detailed disability-impact certification ordinarily required.
Importantly, the underlying DTC legal eligibility criteria would remain, and CRA could request additional information.
This should not be described as an established universal 2026 application shortcut yet.
Finance Canada released draft legislative proposals in July 2026, so publishers should continue labelling this measure as proposed unless subsequent legislation brings it fully into force.
More Medical Practitioners Are Proposed From 2027
Spring Economic Update 2026 also proposed:
- Allowing occupational therapists to certify eliminating impairments and additional cumulative effects;
- Expanding physiotherapists’ scope to certain feeding and dressing impairments;
- Expanding speech-language pathologists’ scope to certain feeding and hearing impairments; and
- Adding podiatrists as qualified practitioners for certain walking impairments.
These measures are intended for certificates issued after 2026 for the 2027 and subsequent tax years.
Applicants in 2026 should therefore continue using CRA’s current practitioner table, rather than treating the proposed 2027 scope as already effective.
Public Guardians and Trustees Change Is Also Proposed
The 2026 update also proposed allowing provincial or territorial public guardians, trustees and Québec public curators to provide certain certification for adults under their property care who have valid incapacity certification.
That is another proposed measure and should be described as such rather than presented as an already-established general DTC rule.
Frequently Asked Questions
Is the Disability Tax Credit a One-Time Payment?
No. The DTC is an annual non-refundable tax credit that can be claimed for each tax year in which CRA has approved eligibility.
A retroactive reassessment may result in a one-time refund covering several previous years, but that does not make the DTC itself a one-time payment.
Do I Need to Reapply for the DTC Every Year?
Usually not. CRA’s Notice of Determination tells you the years for which you are approved. Some approvals extend for several years or longer.
You claim the applicable amount each approved tax year and reapply when CRA indicates that certification has expired or a new application is required.
Does Anxiety Qualify for the Disability Tax Credit?
It can. Anxiety may qualify through the mental-functions category if its effects satisfy the severe and prolonged functional criteria. A diagnosis alone does not establish eligibility.
Does ADHD Qualify for the DTC?
Potentially. CRA looks at how the impairment affects everyday mental functions rather than granting the DTC simply because a person has an ADHD diagnosis.
Does Diabetes Qualify for the DTC?
People with Type 1 diabetes are deemed to satisfy the therapy-frequency and 14-hour requirements under the applicable life-sustaining-therapy rules for 2021 and later years.
Type 2 diabetes does not receive the same automatic treatment but may qualify where the normal DTC criteria are met.
Can Arthritis Qualify for the Disability Tax Credit?
Yes, if its functional effects satisfy the DTC criteria. Relevant categories can include walking, dressing or feeding, and significant limitations in multiple categories may potentially be considered cumulatively.
How Far Back Can the Disability Tax Credit Be Claimed?
CRA allows approved applicants to request adjustments for DTC amounts going back up to 10 years, provided they were eligible in those years.
Comments 1